If you’re young and broke, you’ve got a better chance of reaching $100M+ when compared to someone in his 40s with a million or two to his name. This is because the older person has much more to lose (likely has high expenses, Career to give up and many other ongoing costs). Oddly enough, we’ve noticed that many people don’t get to even $1 million largely because they spend at the wrong times, ramping up their expenses when the ROI doesn’t even show up. So we’ll go ahead and highlight some milestones on when to do a lifestyle upgrade.
Basics: Someone in their early 20s shouldn’t have high expenses. The expectations of you are low. You don’t need to go to the club and drop $10K on bottle service. You don’t even need to spend a lot of money for entertainment purposes. Using the classic example of a “date” you can easily get away with going to the beach and drinking wine/beers. This is entirely acceptable since no one expects a 21-24 year old to have a lot of money.
Another interesting psychological note that we think goes unchecked. Even if you do make good money, there is no point in showing it. Generally speaking, people do not like it when you have “more money than you should”. If you want to experience this first hand, it is quite common to get “bad looks” on your first couple of business class flights. They look at your face and assume that you have money from “mom and dad”. Instead of being annoyed by this social taboo, use it to your advantage and simply upgrade when you realize you can upgrade your entire lifestyle.
The underlined section is critical. If someone decides to upgrade their lifestyle in sections, something always appears off. If they buy Gucci shoes, but don’t own their own apartment… this doesn’t make sense. If they do buy an apartment but can’t afford to go out to a decent dinner ($100 a person), this also doesn’t add up. From what we’ve seen the people who end up with a lower net worth despite having high incomes try and upgrade in “bits and pieces” versus overhauls every 3-4 years or so.
For the sake of starting a debate here, this is a rough outline on how to increase spending and what we would consider the bare minimum (major city).
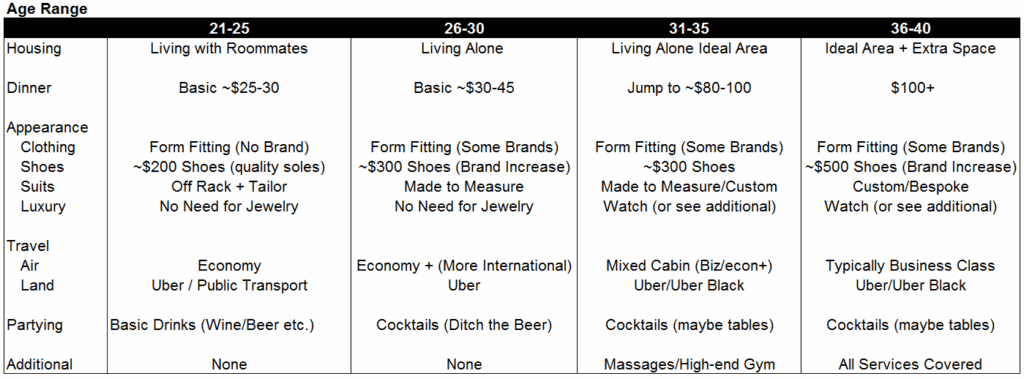
Age 21-25: Our blog targets people in the 21-35 range for a reason, it’s the easiest time to get rich. Most people will overspend because they are making a few bucks (~$100K/year) and think they are now “rich”. This is when a smart person will realize that spending at such a young age is largely a waste of resources. If you’re going to spend all of it then you’re going to negatively impact your social life. It sounds counter intuitive. But. If you’re trying to show how successful you are when you’re young, all it does it damage your relationships with older successful people.
There are always exceptions to the rule but a good rule to follow is “No one wants to see someone younger than them (or the same age) succeed”. If you follow that basic rule you’ll realize why people are so competitive. They truly believe if you’re the same age as them you are somehow “equal” especially if you meet for the first time in a neutral setting.
This was a long introduction to say that “you should spend like you’re a young graduate”. This means you shouldn’t even bother upgrading your life through your early 20s. Even if you hit it big (and many of you will) by age 23 or so… There is no reason to spend a bunch. Why? The ROI is just too low. For what it’s worth we’ve found that age 27 or so is the inflection point and by 35 you can essentially do whatever you like.
With this backdrop we’d say a good framework is to live with roommates your first 3 years or so, 21 to 24 years of age. You can eat at basic healthy places and avoid going the bottle service route (bunch of college people chipping in to sit around a cheap bottle of vodka doesn’t have a high return profile). Find some basic brands that fit your frame and spend more of your time building revenue streams.
Treat the first 3-5 years after graduation (if you went to college), as a very difficult video game. You want to live as cheap as possible because it’s socially acceptable (take advantage of it!) and you won’t have much time to do anything else besides build revenue streams and go out a couple times a week. Finally, no girl you’re interested in will care if you live with roommates under the age of 24/25. If she does care… not a good catch anyway.
The Financials: Roughly speaking, in an expensive city, you’re looking at rent of around $1,500-2,000. Your food costs and drink costs should run around $1,000. Then you’re left with another $1,000 for transportation, a vacation/trip and miscellaneous costs. This will get you to around $70-90K in gross annual income being spent. If you’re a banker you’re essentially saving your bonus. Unless. You’re a smart banker who created a second form of income adding a few thousand dollars a month and growing.
Age 26-30: To reiterate, the chart is just a guideline. Some people may end up living alone a tad earlier but our point is that around this age bracket it starts to damage your social life. If you live alone at age 26-30 this is going to help your social life the most. You don’t need to buy anything or upgrade to a massive high-end apartment, all you need to do is live in a good area of town alone. If you’ve taken your early 20s seriously, you should have two solid forms of cash flow (at least). You should also have a good amount of money invested which means the income you make from investing (stocks/real estate) should add another “0.25x”.
Pausing here, a solid form of cash flow is something that covers all of your *necessary* expenses. This should be 1) rent, 2) food/drinks and 3) utilities (internet included). If you’re in this situation it means that you’re able to invest at least ~50% of your income into new ideas, stocks/bonds/real estate etc. Also. Our 0.25x assumes that you’ve already done this. You should have some investment income coming in that results in about 25% of your total living expenses being paid for. Ideally it is higher (closer to 50%) but 25% is a good minimum goal to hit by this age bracket.
From a social perspective, you can still get away with a relatively basic lifestyle. Instead of trying to “flex” on everyone at this age, go ahead and fly under the radar again. The reality is if you try and push hard into the spending category you’ll run into big competition (guys in their 30s) with 2-3x the spending power. It just isn’t a fun game to play. We’d recommend taking this time for a lot more traveling and simply upgrading the venues a tad.
If you travel in this age bracket you’ll know what countries are enjoyable. You’ll have a better feel for your own personality and you will get a lot more life experience. Some of them will be good (learning a language) some will be terrible like getting robbed or tricked the by locals in some form.
The Financials: At this point, you should be putting significant distance between yourself and your peers. The chances your peer group took the time to build a second stream of income is under 1%. Seriously. Under 1%. Your lifestyle is going to upgrade at the same rate as everyone else. While they got income bumps of 20-30% like you did (Career), they will spend it all to upgrade to this next tier of living. You on the other hand, had a 100%+ bump since you created a second form of income.
The monthly spend goes up a bit but nothing crazy, the two biggest benefits to your social life will be 1) living alone and 2) the change in suits from basic off the rack clothing to made to measure (at minimum). Each month you’ll spend about $2,000-3,000 on rent, $1,500 going out, $500 on traveling and $1,000 on the rest. This gets you into a range of about $5,000-6,000 a month or low six figures in spending per year (gross income basis).
Age 31-35: This is where the “money hose” turns on. Compounding is an amazing mathematical phenomenon. If you’ve gone through and followed the rough 9-10 year guideline you should be set. You should be worth well over a million dollars and more importantly your cash flow is now over 3x what you can spend in a year. If you were spending about $5,000 a month, you’re likely making $15,000 a month net at this point (again could be much higher depending on how hard you worked).
The best part about this age range? It becomes acceptable for you to be “well off”. If you check into your business class flight, you no longer get a strange look from the passengers. No one believes you were a spoiled kid who inherited money and you can drive a nice car/wear a nice watch without any social repercussions. The only downside of this age bracket? You’ll get a lot of questions about how you were able to “make it”. Just deflect them and say it was luck since there is no point in having these conversations with people your own age (“No one wants to see someone younger than them (or the same age) succeed”.
Now the fun part begins, since you can cover 3x your old living expenses you can easily decrease your multiple to ~1.5-2x. This means you can increase your spending to at least $8,000-12,000 or so per month. We don’t know about other people, but if you’ve got $10,000 a month to spend and you’re a single person… you’re doing well practically everywhere. This is 100x more true if you’re location independent. Even if you decided to work a Career, major cities are quite easy to live on with five figures in monthly spending (~$200K gross a year).
Depending on how you want to change your life, essentially you move to the “ideal” part of the city for you. If you were there already? There is no reason to move. The next two biggest upgrades will be your flights (moving to business class at all times possible) and the change to services (freeing up hundreds of hours per year, cleaning/cooking/stretching etc.).
The Financials: Each month you’ll spend about $4,000 on rent, $2,000 going out, $1,000 on traveling and $2,000 on the rest. “The rest” is quite variable here. We don’t know if the person decides to buy a home. They could rent and live a location independent life. They could also give up traveling because they love the city they are in. We just don’t know. What we do know is that the flexibility is there and the gap between you and your original peers will become so wide it becomes uncomfortable. The good news is that the other people who made the correct life decisions will stand out like Ferraris parked in front of a 7-11 (obviously out of place!). These individuals will end up being your new normal contacts.
Age 36-40+: We’re only putting this section in here as a bit of a warning sign. When you start getting closer to 40 or so the “assumption” is that you did make it. This is the exact opposite of the beginning of the article! When you’re young people assume you’re broke and give you a pass. At 40? People assume you’re rich and don’t give you a pass for anything.
If you want to continue going out frequently it’s much more likely that there is a “group” environment associated with it. While there are always exceptions to the rule, it’s more likely that a rich guy will show up with a group of people versus solo. The times you’ll see him going into a club alone are next to zero. You’ll find these individuals go into cocktail bars, hotel bars and other nice venues alone but the clubs are now reserved for pre-planned events since the days of going out hard all night are slowing down.
The Financials: Ideally there shouldn’t be any checking of any spending at all. If you want something you get it and move on.
Key Conclusions: There are a few interesting conclusions here. First: Spending a lot of money can actually hurt your social life. Not only does it make it harder to get rich, it doesn’t make your social life much better. Second: If you make it financially it is smarter to build out that passive income flow from real estate and stocks before turning on the “money hose”. You’re going to be well off buy still relatively young so you can be a bit more cautious. Third: All of the age brackets are certainly guidelines. If for some reason you make it to $10 million by age 30 for example… you can just jump the spending to the 40+ level since it’s irrelevant. There is something odd about turning ~30 years old, where spending is no longer seen as taboo. Fourth: your social life will change. This is not something that is preventable in our opinion. If you’re not changing social groups over time it usually means poor decisions were made. Attrition alone will take your original group of colleagues and dwindle it down to 1-2 of them. The good news is the other people who made it will stand out. Fifth: money is just a tool. Unless you make it to huge numbers of $20M+ it’s hard to tell the difference between someone spending $15,000 a month and $20,000 a month. This is why your preferences will change quite a bit (working less) unless a large opportunity presents itself.
Perhaps I’ve been lucky thus far, but I haven’t encountered the envy of being someone fairly successful for their young age.
I just turned 21 a few weeks ago, and am currently doing a six month fellowship at a tech company’s policy team.
The people closest to me in age (both in the same position as me) are 26, 29, and everyone after that is mid 30s and above.
The majority of my co-workers have MPA/MPP’s or JDs, and/or extensive experience on the Hill. I’m taking a semester off before heading back to finish up my final semester of undergrad.
If anything, I believe it has had a positive effect in my career—I garner respect in the workplace immediately (because people think I must be qualified to be here at this age), and amongst peers, as people are constantly reaching out to me in person and on LinkedIn to network and chat.
During interviews, I’ve always had my age brought up in a positive light, and have also made many meaningful connections with like-minded successful people my age.
Awesome! Yes technology is typically a lot more flexible and focused on results.
I’m getting close to 40, and doing well. Just curious what you consider to be “making it” by then financially is.
Enjoyed “Efficiency” quite a bit, only regret is not having it 20 years earlier
Our rough numbers are in triangle investing.
It took me a while to learn that it’s important to hide my success. Even my friends got jealous and competitive. Now when people ask what I do, I tell them a home business that doesn’t make a lot of money but gives me lots of free time.
That seems to satisfy them that I’m just another regular person, and one who just goofs off — not too ambitious.
That works extremely well.
Typo “21 to 21”
Fixed
Small typo:
“With this backdrop we’d say a good framework is to live with roommates your first 3 years or so, 21 to **21** years of age.” Think you meant 24/25.
Fixed
Great post and I especially like the analogy on playing a video game in hard mode when you’re young (I’m 22 and that’s exactly what it feels like).
That being said, I’m curious why you don’t factor in online biz expenses as part of your budget. As I’m sure you know, getting a recurring revenue ecom business off the ground from 0 to 1 requires a not insignificant amount of money per month (testing traffic, research software, funnel software, etc.). Perhaps there is a monthly amount of spend you wouldn’t recommend going over – I’d be curious to hear it, just given that many of us are working banker hours and can’t afford to waste our weekend time with constant trial and error if we don’t make the investment in data analytics/tracking/premium forums, etc. as you know.
We put that under your expected income from biz. This is why we assume it takes around 3-6 years to start making money.
If you lose money, it’s tax break time anyway.
Costs around $50K before getting decent at making money online. So that becomes a rounding error at age 32-35
Thanks for the quick response. Looks like it’s time to make that s-corp. I’ll keep grinding on the side biz and will think of a more succinct question for the upcoming Q&A.
Cheers!
I Don’t expect details but are you drop shipping, creating products
,or rebranding?
rebranding (private labeling) and working to build a scaleable brand in the eSports market.
LOL at your comment about getting looks when checking into business class flights. I just had this happen to me last week. Just turned 30 but look much younger and someone even made a condescending comment asking me if I was in the right line. Just made me laugh because I immediately thought of this blog.
Yeah the people in their 20s who don’t get the condescending comment look old for their age.
Consider it a complement envy = win!
Interesting prospective shift.
To think I was going to upgrade in bits and peices before this.
Right now I am at the house with zero expenses. About to hit the investments and side business hard for the next year.
All my peers are spending 1k a month for a shit apartment and blowing out on the weekends.
I understand the target market is 21-35yr old’s in the top percentile of income, but this typically happens if you didn’t stumble in your early teens/20’s. Would you be able to tailor a post similar to this but for individuals starting a little later. Say the target market of 25-40yr olds vs 21-35 starting with 20k in cash.
The biggest life changing investment I’ve made so far is cutting off my peer group. They’re average people, holding me back, yearning to settle and live a dull, flavourless life.
I find this very difficult. Im 34 and have my friends since 7years old. Did you stop cold turkey?
If you find it difficult, they are probably sucking you dry. Leave now.
If you find that difficult, think about what quality of life you want. Consider this:
Does a 27 year old “friendship” mean more than you being happy, healthy and wealthy for the rest of Your life?
Do you want to spend the rest of Your Fridays at the local joint, complaining about the job, taxes and politicians while refreshing Your Facebook profiles 5 times a minute and yapping on about “the good ol’ college days?”
Do you want to be held Down by Your peers who don’t support you because you have to stay at home and work on Your business goals instead of going fly Fishing since it’s the one weekend when their nagging fat & ugly wives don’t go out to cheat on them being some Rich 60 year old’s sugarbabe?
Do you want to see life slowly sucked out of Your soul, seeing Your hairline recede, Your paunch grow so that it looks like You’re pregnant With octuplets and feel those joint, back and neck pains slowly but steadily torturing Your body? All because you bought take away junk Food while driving the kids home from School because “you didn’t have time” to Cook dinner?
Do you want the New video game console that’s being released every 4 year or so along With some bull crap RPG game to be the thing takes up Your “personal time”?
Does this at all scare you? I know it scares me!
You see, until about a year ago, I was going Down this path myself.
I’ve lost 4-5 of my best years! At age 33 it’s not too late, but time is ***not*** on my side. That’s why I had this awakening last July.
I haven’t gone cold turkey. I’ve simply told my peer group what I’m up to, and I’ve seen them slowly drift away. They were time suckers anyway.
The hunt for true friends and acquaintances goes on. I live in rural Norway, meaning I’m surrounded by hillbillies & rednecks. Kinda like if I lived in Wyoming, I guess.
Right now I’m focusing on building my business. And taking care of my 2 year old daughter part time.
Once she gets old enough, I’ll move to some better place and find cool people to hang out with.
One word: FREEDOM! That’s more worth to me than a bunch of fat, lazy people.
Hope this helps you. Get out of the mediocre life while you still can!
Damn dude. I need to do this desperately.
I spent the whole summer hanging out with my old friends while I just started working.
To quote Uncle G: “Pay the price now so that you’ll be rich tomorrow!” or something like that. I’m sure you get it.
Relative to your age, you’ll have to put in a certain number of hours every day. I’m 33 and all I can think of when I’m not spending quality time with my daughter is (yet another quote from Uncle G): WHO’S GOT MY MONEY!
i had a big one time payout, and my really big upgdrades have been 1. clothes 2.cleaning 3.food 4. flights. and 5. fitness. My payout took me from an on-call who worked in a casino which meant no set hrs and no set sleeping patterns. that affected all aspects of my life. Now that i set my own hrs and have more $$$ all of those aforementioned things have improved by leaps and bouinds
Online sales?
gambling. Hit big enough to chill. The big downside at 1st was boredom and losing people i spent time with because they were working and i didnt have to. That boredom one is huge because if you dont fill it woth some good habits( fitness, maybe some volunteering, healthy social life) you will most definitely, especially if you live in a robust city fill it with bad habits (drugs indulgence in hookers, drinking all the time) So once you have those good habits down then you spend the $$ on high end things that support good habits. Better gyms, juicers better produce, good shoes and better fashion for social life,, but not too flashy
My experience differs from yours. I’m 25 and look much younger. I fly business a lot of the time for work and have plenty of higher end gear but not the highest end (Armani Suit, Ferragamo shoes/belts, Rolex, Tumi etc.). I have yet to find anyone give me any odd or bad looks. Usually we end up chatting business on the plane and we exchange contact information for future ventures. If you’re social, well mannered, and polite it’ll pay off dividends for you. Dressing like I have my shit together (which I do) has made me countless contacts that have directly converted to growing my revenue and net worth. The number of conversations that I have been apart of because we found common ground both being watch lovers is massive. You’ll get great intellectual conversation and learn about new investment strategies too (but you need to bring something to the table yourself or why would anyone want to talk to you when you aren’t perceived to be their equal).
If you want the ability to have lots of face time with high powered individuals, flying has always been great for me. You get 1-4 hours of uninterrupted time to chat and network. Some folks want to talk business during that time others don’t. Some want good conversation – be social, be well rounded, well spoken, polite, and able to discuss a multitude of topics at a high intellectual level and you’ll be surprised with your results. At least I have in my experience. That being said, don’t be some ignorant dumbass irritating someone trying to relax or who doesn’t want to chat business. Assess the situation and discuss topics that everyone enjoys. You’ll find many similar personalities flying business/first class.
For reference, I save/invest 100% of what I make from my day job and live off of my investment income and side companies that I own (and that I continue to grow).
You left a key clue in your post on why you’re not seen with distain! We are reluctant to reveal why yet but the reason for no commentary is in one sentence in the post.
Congrats on all the success!
because he looks like he’s 20! No one is going to hate on a college kid. Everyone is going to assume his parents are paying for him.
Nah much more specific ha
Bonding over watches… They see a younger version of themselves in him.
ESE – congrats on all of your success! It’s impressive to see someone of similar age achieve this level of financial success.
If you don’t mind me asking, what kind of business did you start and what kind of startup capital did you need?
Looking young and having money does have perks. Trust funders assume you’re another one of them when you’re really self made. It allows an additional avenue to network through (D-Train).
To RE: I own an engineering consulting firm, plus I deal in lots of real estate development (which has made me a SHIT ton – done over 7 figures worth so far and more underway). I’ve had full rides through undergrad and grad school and great paying gigs at the same time. I was able to finish grad school at 23 with multihundreds of thousands net worth and used that to supercharge my investments at graduation. Now I am able to invest 6 figures a year to continue to allow the compounding.
Most everything I do, I run solo but I have a few smart people that help out on some components of the work I do. Dump all of the leeches who add 0 value to your life it’ll pay you dividends in the long run. If you have any other questions I’m happy to help as time allows.
“Now I am able to invest 6 figures a year to continue to allow the compounding.”
This is usually where the snowball begins, something about investing $100-200 that really makes the math go crazy
ESE – Thanks for the detailed reply. I currently work in REIB and am definitely interested in RE development in the future.
Issue is development requires either: a) long track record and/or b) significant startup capital to attract LP investors for projects. Did you parlay your engineering consulting income to RE? If so, what was your initial GP investment? I’ve heard tax credit deals are the easiest (least skin in the game) to get started.
I’m looking for a way to increase my income substantially in the next year, but the 80hr/wks in IB leaves little time for biz opportunity. Trading time for money (even when performance based) sucks.
RE, remember how I said I work with a few smart people? I work with an Architect who can do the due-diligence on the structures we want to rehab or designs for new builds aspect of the process. I track down the properties, build financial models, and develop the strategy. I bring lots of money to the table myself and I have a small circle of people I offer to join me on deals if I can’t pull it off myself. I surround myself with other investors like myself and have walked them through past deals, proformas and discuss past performance. Then some are ready to hop on the train if you can make them money at target rates. If they aren’t not a problem, I can figure it out myself. I usually try and purchase all cash from distressed sellers and then redevelop their terrible situation. You can buy up properties pennies on the dollar and have assets that banks will allow you to refinance cash out for future deals. You mitigate acquisition fees this way as well and optimize profits. In the current market, there are not abundant deals to be had that will achieve great ROI’s, thus better to purchase cash and not tie up cash flow servicing debt. You only want to service debt when the next property has been identified and use the refinance money (if needed) to make future deals. The goal is to not have shit tons of liquid cash getting shit returns while your leverage returns are great. Total returns are everything to your investors. You also have to identify your strategy, are you buying and holding (that will affect how you develop) vs flipping in 7-10 years like a PE firm does and calculating your IRR and when the J-curve effect pays off. You need a deep understanding about all of these items before people are going to entrust their wealth in you.
I haven’t played with tax credit deals. I go all in on my deals and do everything to lower my costs, fees, etc. If you have confidence in your strategy you shouldn’t be afraid to have skin in the game… also many investors look for the RE developers to have skin in the game (if you won’t invest in the deal, why should they)? First project was into an abandoned multi family complex. I fronted 75k on the deal and other investors went in the rest. That development gives unleveraged returns of ~13% not including appreciation where the real gains are coming from. When future projects come up if that deal is tapped the leveraged returns will jump to 33% not including appreciation. The property has appreciated 156% in around 3 years.
For tech I can work 35-60 hours a week and have the rest of my time to play ball on investing. Tech is a great way to work side hustles and grow your wealth.
RE can grow income proportional to your capital but it does lack the scale-ability benefits of tech technologies.
My best advice to you is think of yourself as a business. You are your CEO that makes all the decisions about your cash flow (income). How do you want your shareholders (you) to benefit from that cash flow. Everything I do is about maximizing shareholder wealth thus why I’ve been doing well. If you want to live high on the hog as a CEO your shareholders will have less left for them. If you reinvest the cash flow you get business growth. Master this principle for yourself, then apply it to any business you make and you’ll become as rich as a good (assuming you aren’t an idiot).
Following those principles I refuse to spend money I earn actively. Active money that is earned is used to create cash flow that I can then spend. Why work for money to spend it? Work for it once and make that 1 hour of your time work for you into perpetuity. Just my .02 though many don’t follow that… but they follow the pack and get pack like results.
ESE – Appreciate the repeated reply. RE is a great investment vehicle and it seems that you have created substantial wealth for yourself over a short period of time. I’ve rarely, if ever, seen someone accumulate 7 figures in RE over the span of a few years (< 5), unless they’re starting somewhere in the low six figures (75k is definitely a strong start but hard to snowball that to $1+ mil). Closest reference point I have is a client that has $35M of equity tied up in multi family in the mid-Atlantic region. No college degree and currently in his mid 30s – completely self made, but 14 years in the making.
I rarely encounter someone of your caliber on a day-to-day basis. Especially given your accomplishments at such a young age. Currently trying to fix my own personal financial “Machine” (just about everyone intelligent finds Ray Dalio’s book to be a useful coaster – except the masses – they actually read it). Would love to take this conversation offline if you’re willing (under the premise that both of us are extremely busy professionals – albeit with opportunity costs orders of magnitude apart).
Thanks!
7 figures worth of real estate developments doesn’t mean I own all of the equity (investors are in on the deal with stakes too). I have definitely made a lot doing it though: for my efforts and with my investment strategy thus why I can attract capital on deals to make others money as well – but luckily I’m allowed to be picky on who I let go in with me. I would say there is a good chance I hit 7 figures with my RE portfolio by the time I’ve been doing it ~5 years. However, RE isn’t the only component of my NW.
Sounds like he got in at a great time and was able to mop up in the crash… unluckily I have to do a lot of work to find properties at good deals… not like the good old days from what I hear!
Sure, you can email me at hustler4life7svn@gmail.com.
Reciprocity. So signaling with clothes/watch .. so I m 39 owning a a small asset mgmt biz + work for a billionaire family office.
Now: I would ‘test’ quickly knowledge about watches. Then test investment knowledge. If there is substance then there is value for me. Since he is younger and on the way up it is a great contact.
Simple.
Haha. I was at MIT a few weeks ago and I saw someone with a Royal Oak AP, I said I love the AP and he said, you know what I’m wearing? I knew because I was eyeing the Royal Oak and Nautilus for myself but decided against them but not many people are familiar with the 0.1% watches. After that we became good friends over the next few days and he said if I wanted a job in Boston he could help me out… My Rolex obviously couldn’t compete against his AP but we found common ground on our love for watches and both having technical backgrounds and went from there. People love to talk about their timepieces, it’s a great ice breaker.
People remember how you make them feel more than they remember the content of your presentation. Apply that basic piece of psychology to life and reap the rewards!
Great post guys.
I would add one other big reason why it makes sense to upgrade your lifestyle in spurts and to only upgrade in a significant way when you really make it – once you have made an upgrade, it is psychologically really hard to go back down a level in the even that things don’t work out.
The only thing worse than always being poor is having been rich and then being poor. When you’re used to luxury, it’s almost impossible to go back to being without it. I’ve seen it happen to too many family friends who were reasonably wealthy, then overspent (yachts, mansions, divorce w/ wife, etc) and ended up broke… those people usually end up stir crazy.
Private medical. (England)
Excellent post.
Lifestyle inflation is often driven by one’s environment. I’m at a junior/mid-level at a buyside shop and it’s ubiquitous here. People buying expensive watches, cars, going on flashy holidays. Personally, I try to stay away from the whole splurge fest.
Invariably, people get “used to it”. A big apartment with a jumbo mortgage, 911 convertible, AP on the wrist, and no freedom at all (NEED the job to pay the bills). Doesn’t make any sense to me.
Solid post, enjoyed it. Early 30’s, worth over $2M (less than 15% in $401K)…so i guess most would feel like I “made it”…However, As someone who wants to have a family in the NY area, I’m going to need to continue on the gas and keep pushing. The challenge is that I don’t have a second form of income (side biz/website etc) outside of my public investments etc. The onus is on me to to continue grinding and working in finance it is a grind and then some. Having a family will likely incur some costs, but assuming I can generate an additional 12ish% of my NW annually through saving and investments I should be good to go with 5M plus in a decadeish…seems like so long!!!!
Good luck! The stress will be dependent on your spouse if she works should be easy and if she doesn’t will definitely need to hit the gas hard!
Thanks for the quick response. She works, but her income is about 15% of the total income. We combined make about $500K of which we can perhaps save $100-130Kish annually. With 6%ish returns gets us to $250Kish of growth a year…Not even sure $5M will be enough in the NY area assuming we have multiple kids etc.
Is the point of the high end gym to make contacts? Because outside of that I don’t understand the point. I work out in an old school iron gym for $10/month. I’m there to lift heavy and then leave.
Yeah that’s part of the point… but if you aren’t doing cardio, stretching, swimming, etc. then you’re doing the long-term you a disservice. Generally speaking, high end gyms have better versions of the aforementioned facilities.
Fantastic article. I grew up in a lower-class household, and just landing a job (not a career yet) in tech making more than my parents have ever, combined; I started to get excited about the all the new shit I could buy.
Brand new car, designer clothes, a nice apartment, etc. I was ecstatic to “flex” on the kids my age (~21) who are still in college. This was a solid reality check.
Thank you for helping me keep focused on the real prize. Living modestly while building my second stream of revenue and moving to a career from my job, to make it before 30.
Obviously, it would be beneficial to push my standard of living, even slightly. What do you guys recommend to increase in terms of quality? Eg. eat healthier, getting rid of clunker-car, nicer clothes/shoes, etc.
Awesome article and comment section – as someone whose not yet made it this gets my head in the right place!
Short story and accompanying question – Im about to turn 31 and wish i came across this sort of advice and guidance when i was 18. After high school i was quite antisocial and lost in life, my family was doing quite well financially and i (naively) assumed id never have to worry about money in life, so focused on a getting a fairly useless degree (psychology), travelling, life experiences, self improvement, wasting time and odd jobs here and there (part time supermarket, etc). This dreamworld i was in came crashing down at age 25 when i found out my family was not that wealthy and had in fact been living the life for the past 7 years burning through capital and having no real income.
It was a rude shock to wake up at 25 with no career, no skills, no direction and no family fortune to fall back on. I was lost for a while working random labouring jobs that paid well but offered no future or skills growth but after countless months surfing the net for job ideas and direction i came across affiliate marketing and decided to throw my hat in, learn the skills and hopefully make it big.
I did this for a few years (labouring job by day, affiliate marketing by night) and by age 28 had nothing to show for it profits wise – this was especially disappointing as im a logical guy with an above average IQ who worked hard years trying to solve the affiliate marketing puzzle, so it was personally and financially crushing.
Not seeing a future here i managed to use my affiliate experience and skills to get my foot in the door at a local digital marketing agency running Adword accounts for clients – and after a few bumpy months i really excelled at this and became quite competant at it with my largest client spending over $1500 per day and very pleased with his results.
At the time though (aged 28 and 12 months into the Adwords job) i couldnt see the forest through the trees and was feeling the pressures of being close to 30 and earning a very basic wage that just paid the bills, so i ended up taking a blue collar government job (chasing money essentially) which paid significantly more (more than my accountant and engineering friend with 10 years of experience) however it offered nothing in the way of valuable skills or experience in the outside world.
In the last 6 months though ive had a real change of mindset and now see the long term value in the acquisition of high value skills that will lead to a huge payoff down the road vs a high paying deadend job that im currently in now, as i also value the sort of person i become as i go through this journey just as much as the skills and money i acquire.
So my question is – just based on my background and as a nearly 31 year old single guy with no commitments or obligations, who loves reading, loves self improvement, has high ambitions in life, who works hard, has a logical problem solving brain and can present well socially, but who has on a professional level wasted those formative years of my life – what would you suggest is a way to salvage my situation and achieve something resembling the sort of financial success discussed above in a timeframe that will mean i can actually enjoy some of it in my youth?
I don’t know about this…. I know very few people 9 years into their working life who are making $250K annually… that is a pretty big leap…
Also, I know many many 40 year olds (I just look around me) Who are broke as shit!
Lol time to get new friends and get outta wherever you hang out