In short, we’re screwed. While we can fight off the virus and potentially stave off mass casualties, the economic damage is the real issue. Back in 2008-2009 there was a *centralized* issue. The issue was that many mortgages were collapsing. So the solution was drastic and simple, lower rates and inject cash to the major banks to avoid a cascade of defaults. In this situation we have a distributed attack on the system. How do you bail out restaurants, airlines, hotels, malls, casinos, cruises and real estate all at once? The second issue is that the distributed default is not easy to contain, if someone runs a small business with $1M in revenue and $100K in profit, it means his monthly expenses are $75,000! This is a big issue. Even if it’s a single month at 0% interest… It would take the person 9 months to recover. Now scale this up and spread it across the united states. That is the current situation today.
Explanation: The more sophisticated readers can skip this part. In simple terms many companies operate with leverage. This means they have more debt than cash. So imagine you have $1M in debt and $200K in the bank to run your small business. Well.. if the business makes $1M per year, you’re probably okay. If the business has slim margins (restaurants, airlines, casinos, etc all have slim margins), then you’re in trouble if your annual income was low.
What happens? We can use a simple real estate example. Forget the “regular upper middle class consumer household” they are actually okay if they have a single mortgage. Go to the bigger picture. You have a 1,000 unit apartment complex in a major city like Las Vegas Nevada. Suddenly the entire casino industry shuts down for 2 months. This means people cannot pay rent. If they cannot pay rent that entire apartment complex now defaults. So you’re not looking at a regular mortgage default, you’re looking at a corporate debt default (even bigger).
What happens to “fund managers”: This gets even uglier. This week major hedge funds have fired Portfolio Managers. If you think all hedge funds are “hedged”… Well many are simply wrong. Even Citadel and Millennium have fired PMs this week and those are some of the better performing funds in a market neutral book (market neutral for newbies means they have to be long $100 of Stock A and short $100 of Stock B). In theory, by being long and short the same amount, you should be “flat” if the market goes down. As you can imagine with huge volatility this doesn’t work. Why? Well the books are levered up 5x!
Lets review in basic terms. If you want to own say Google, you have to be short something else in internet say Amazon (again this is not correct exactly but explains it well to regular readers). So you have $1M to invest. Well in order to generate returns you lever up the book. You have $5M to invest into this position. So lets say you short Amazon and go Long Google. $2.5M is short Amazon and $2.5M is long Google. Great. Assuming no wild swings, you will outperform if internet stocks go up and google does better than amazon. If internet stocks go down and Amazon goes down more than google, you’re set!
Seems fool proof. Until? 20% swings. Look at stocks in the S&P 500 and you will unlikely ever see this ever again (we hope) over the next 20 years. It could get worse as we don’t think we’re anywhere near the bottom. That said, a 20% move would force you to LIQUIDATE that google position. That is absolutely crazy. Since you’re 5x leveraged if you don’t have money to support the margin call, they force cell the asset… You’d think it ends there? No. It gets worse.
Now imagine while this is happening, you have had 5 years of record performance (Citadel and a few other funds are up substantially the last 5 years using this long=short construct). Now you get people calling “i need to pull out $5M since my business is getting crushed” from wealthy clients. So not only do you have to deal with the margin calls, you now have to begin selling assets to cover the $5M redemption (redemption is finance speak for customer asking for money back).
Welcome to what we’re seeing today. We won’t even go through the Oil fiasco as that’s too painful to even write. Texas is going to suffer if numbers stay as low as they are (oil prices) and we’ll leave it at that.
Fed Policy Out of Bullets: Since interest rates have been low for so long, the interest payments were easy to hit. If you take $1M loan at 2%… That’s only $20K a year! Incredibly easy to find a way to generate profits of just 2% on $1M of capital (so everyone said…). Then you have a strange event like this, a complete out of the blue viral severe pneumonia. Suddenly those business that were making profits due to cheap debt, borrow at 2% and get 4% returns… are borrowing at 2% and seeing – 50% “returns”. Leverage cuts both ways.
If you believe -50% is not feasible we suggest you look at real estate or casinos as good examples. You have a sudden revenue drop to zero for at least a quarter (we doubt it’s that short), and you’re looking at $0 revenues and hundreds of millions in losses. Unless you fire people of course… which is why layoffs are occurring immediately. Remember the small business example set above, if you have zero revenue, you have to borrow to cover that month of expenses. Now imagine that monthly payment is $50-100M not $50K… Now you see how hard it is to “get that money back” with future earnings.
Since we live in unprecedented times, the Fed is attempting to help create “liquidity”. This means all of those margin calls are being funded with 0% interest rate money. Also. The government intends on giving individuals money straight to their bank accounts (sending them checks!). While this is fine for now, it doesn’t solve the long term problem. If trillions of dollars of revenue goes to zero… expenses were paid with 0% debt… How long does it take to repay the debt? We don’t know. But. We’ll say it is likely a very very very long time. If you want us to guess, unless there is a miracle, you could see 3-5 years before real growth and pay down is seen. This is simply a guess based on the environment continuing through Q3. If the virus does come back in Q4… all bets are off as thousands of business depend entirely on holiday season earnings (not to mention skiing in the winter).
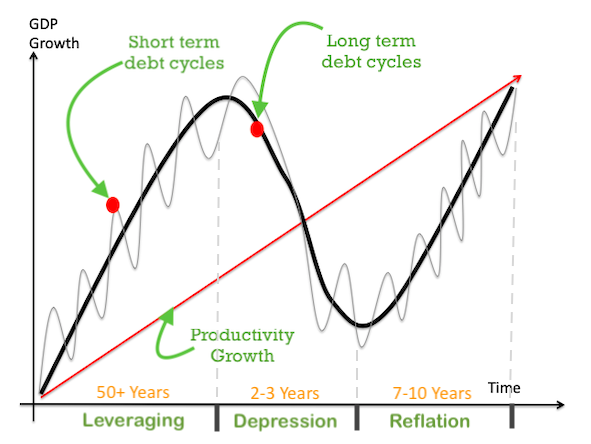
The Fed had two choices: 1) take rates to zero – Check and 2) start printing money – check. This is a bandaid but we’re now building a massive debt burden even if it as 0% interest. Also. It assumes that everyone returns to “normal” when we get through this mess (doubtful, again an opinion). So you have a cascading debt load, consumers can’t pay bills, those companies are levered up, they can’t pay the debt, they get 0% debt, they have to pay all that debt back with future cash flows. You can see the issue.
“Just print money”? This definitely will help. We’ll actually go on a limb and say that’s better than the debt idea for now. We know the crypto community will hate that comment but it sure beats seeing people unable to pay for food. You’re better off with the second option which leads to? Hyperinflation or even Stagflation. If you print too much money, prices keep going up and people are still unemployed creating a massive issue – stagflation.
So there you have it. Two choices: 1) push out the pain again with 0% debt and pray the business environment goes back to normal quickly or 2) give people money to prevent default and risk asset price inflation. By the way, we mean “give people money” literally. As in sending checks in the mail.
What Do You Do: First of all, thank you for all the emails the past two weeks from the people who actually took our advice. We’re thrilled you’re financially better off and mean that seriously as we don’t even care about being right anymore, better to see people avoid a massive blow up (having a month of food is huge in a lockdown). What you should do is much of the same. We’re in markets that are likely going lower (opinion) and if we’re wrong and there is massive printing leading to inflation, you still hold some stocks from way back in 2012-2016 so the cost basis is 50-60% lower. So you’re good to go.
Instead any more you get you have to keep it simple. 1) retain 12 months of cash on the books at all times, 2) all income you get you want to buy “store of value” this is gold, crypto etc. While people believe the store of value narrative is gone.. it isn’t. Re-read the section on margin. If people had billions of dollars levered up 10x or more, it means a 10% price drop would liquidate all crypto investors immediately. That is what you saw. Same with gold. While gold investors are less levered up. Investors have to sell gold to fund their losing positions. Any time leverage continues and margin calls ramp up… this means everything goes down temporarily and volatility spikes.
Since we have to give a recommendation now, the easiest one is the same as a month ago. Keep cash balance up to 12 months of your expenses. Just focus on that and take your costs to zero (impossible but you get the picture). If you are already there and have 12 months or more, go ahead and buy store of asset products like crypto and gold.
In terms of your work there isn’t much you can do. If you’re in the Ad space, the vast majority of you should probably take spending to zero. Yes zero. Unless you’re in an industry where benefits are being seen today, just take your spending to zero if you’re already losing money. On the Career side of things, this is not the time to be “lazy” catch up on the news when you’re done and spend your time being helpful to your employer. Thank your lucky stars you’re still employed at this point.
Predictions of the Future: We *hope* for the best but prepare for the worst. Our “standard case” not worst case or best case is that this virus lasts for over 3 months. In addition, we think it comes back stronger in Nov-Feb time frame. We’re not being pessimistic, we’re simply looking at facts from prior corona virus cases. The last 6 of them never resulted in a vaccine so we don’t know why this one will suddenly be solved. The answer? We recommend you personally stay safe and if you’ve been acting paranoid keep that up for another 9 months or so. You will be laughed at today and it’s worth it. Better to be laughed at and take the risks to near zero.
In terms of industries we have some bad news: large gatherings (casinos, concerts, cruises etc.) are going to see long-term issues for at least a year after resolution. Why? There is just no mathematical way this is solved in a couple of weeks. To the low IQ people who said “this is just the flu”, “store of value is done for crypto and gold” and “will be back to normal quickly” it’s best to go ahead and delete all of those comments. They are incredibly uninformed. Even if the numbers get “better” in two weeks, you don’t want to have people come back together because it will just spread… AGAIN. This virus is asymptomatic which means you can catch it and have no symptoms. We lost control of where the virus is and by quickly going back to crowds you’re just going to spread it again.
Think Through Risks: It was fascinating to see how people understand “big risks”. Tail risks and things like that sound fancier but we prefer simple english. a “Big risk” is a systematic uncontrollable risk. In plain english: 1) you die or 2) you lose everything. This is why we went full paranoid with this virus, one of those two risks were clearly present. If there is a chance of losing everything you have or dying, you just don’t take the risk. We don’t care how strong, healthy or intelligent a person is. They do not have the capability to avoid a airborne microbe that can infect you with a debilitating lung infection.
On the positive side of the ledger, this is also why things like crypto and gold exist. In a world of absolute chaos, what can be used as money besides “paper”. If we enter hyper inflation like Germany in the early 1900s… those dollars are going to be worth nothing. To be clear. We really really doubt it gets to that but the point is the same. Always have a 5-10% hedge (if you can afford it) or a 1-2% hedge (everyone can afford this) against a catastrophe. If it’s asymmetric to the upside you *must* own the asset. If it is to the downside, you must AVOID it at all costs. COVID-19 is the downside.
Thank you so much for your advice. As a Marine stationed overseas, I am one of the “losers” you discuss. Didn’t understand money, got married too early, made poor choices. Discovered your blog 1.5 years ago. Still don’t have a business yet, but am significantly better off financially due to your advice. I bought some physical gold a couple weeks back, and have been only buying bonds, and have a solid emergency fund in treasury notes and cash. I have a wife, 3 small children, and a baby on the way. You have made a huge positive impact on our ability to weather this storm. Unlikely this will ever happen, but if you ever need help, I will do what I can.
Semper Fi
Charles
Nothing from us just work to keep the ship afloat
Don’t understand – yes earnings are washed for a quarter or two (assuming this is just a 3 month outbreak). Yes, S&P still needs to go lower (15-20% by my math). But why is macroeconomic growth going to be Zero for the next 3-5 years?
Just do the math. Assume 6 months impact. That’s actually 2-4 years of losses. That assumes revenues go straight back to normal levels (no fucking way). So this needs to be solved fast.
I’m with WSPs.
JP Morgan called Depression in Q2 followed by Deep recession of several years.
We’re entering some dark times. One look at the Dow 12 year chart shows this could be a cataclysimic crash, it is headed straight down I’m talking circuit breakers several times a week and FED dropping nuclear bombs on sunday nights( 1% cut+QE.
Stay safe..
Thanks for the post, guys. Helpful baseline for us who don’t follow all this closely
“In addition, we think it comes back stronger in Nov-Feb time frame. We’re not being pessimistic, we’re simply looking at facts from prior corona virus cases.”
Interested on this statement, why do you think there will be another outbreak on November? Based on previous corona outbreaks or why? (I couldn’t find any previous outbreaks doing a semi quick google search)
Just look up viral diseases and their history
Theres a good documentary on youtube about the spanish flu. Warmer weather tends to slow down transmissions. It upticks in colder weather as humans spend more time in close quarters.
The viruses also tend to mutate so there are waves of sickness.
It’s based on the seasonality of flu outbreaks…with cold, dry air the lungs are more susceptible to respiratory infection. However, for pandemic flus like 1918 and 2009, the uptick occurred much earlier in the year than ordinary seasonal flus which aren’t novel infections. Some people have commented that since the Southern Hemisphere is also currently experiencing this outbreak, we might not see much reprieve over the summer. That is, unless it spirals so far out of control that 1/3-2/3 of the population has it by then. I’m still betting it doesn’t get quite that bad but has another spike in the 2020-21 flu season.
I should also mention that this is a different virus than the seasonal flu. Previous corona virus outbreaks include SARS and MERS. MERS is a bit different, causing gastrointestinal issues (remembering off top of my head…sorry if this isn’t quite accurate), and having a much higher mortality rate. I found the data about UAE and corona virus testing posted on OurWorldInData morbidly entertaining with regards to the higher MERS mortality rate…like, they aren’t fucking around with this.
Fantastic article. Beginning to wonder if the US is immune to hyperinflation simply due to the fact that usd is the global reserve currency. It is still backed by tangible strengths like the US military & food supply (accounts for overwhelming amount of global food supply). In addition, the US continues to be the easiest place to do biz current situation notwithstanding.
Are negative rates possible in the US? And if so, to what end?
>Thank your lucky stars you’re still employed at this point.
I got laid off this week (engineering!), high performer but non-essential to keep the biz operational. Company laid off everyone except 1st & 2nd eng hires (I was #3 — got paid too much). Support/ops/etc got cut down to 1 in each dept too. Investors called and told them to reduce burn as much as possible and as fast as possible. I’ll be alright, got a severance + separate income steam + ~6/mo cash position (Can get it to ~8-10/mo once I cut expenses to barebones, not inc severance).
Have been following COVID19 since Jan (WSP for years too), so wasn’t _that_ surprised + and prepped for this scenario. Can only imagine how rough its gonna get for everyone else. Recruiters I’ve spoken to haven’t heard of any COVID19 layoffs in tech yet, getting something lined ASAP before the market floods with other tech layoffs (interviewing with msft/goog/fb/etc in the next week)
Shits rough out there boys, stay diligent!
There have been some COVID19 layoffs – but everyone is keeping quiet (see Bloomberg’s NDAs).
I’m in the same situation and starting “onsite” interviews in a week, best of luck and maybe we’ll work together.
I assume in “Well the books are levered up 20%!”, you meant to say the books are levered up 5x? (could easily see some readers misinterpreting as 1.2x leverage).
To add to your data points, know of number of other highly levered funds that are firing PMs like crazy. In addition, quant funds are facing difficulties because most models/networks didn’t foresee/ appropriately handle this level of volatility combined with illiquidity (wide spreads don’t even help market makers because the blowout risk of the market sharply moving in other direction). Some vol. funds making bank but aside from that looking like a bloodbath. When shit hits the fan, everything liquid becomes a source of capital.
Correct fixing it
It’s amazing hearing people you think are very smart say “It’s just the flu.”
Wild.
Clearly they don’t understand asymmetrical risk.
Either way, followed your advice and I got fully prepared for at least 6 weeks of groceries without leaving the place.
Kept rent to under 7% of income and in a position that I don’t believe will be terminated, as long as the company survives this…
Thank you. Seriously, thank you for the advice over the years. I still think the future is bright and believe a lot of millionaires will be made from this drop. Depends how the dominoes land.
To the younger crowd reading this.
Build. Skills. Now.
Your peers will be sitting paranoid and/or wasting time with Netflix or binging the news. If you’ve been following WSP’s advice you should be locked in your place; take the time to beat them by rapidly building skills.
Good luck all and hopefully you’re safe.
Any particular advice for young people? Just heard college might get postponed till September (even December) …
Just stay in like a monk and learn skills?
No change from efficiency, you can’t do anything so learn sales now.
Fuck…. Great post… Thanks, you put me in a position that could very well save my life. Can’t thank you enough.
Just glad you’re not getting killed by this, many are not so lucky.
I’m going to go out on a limb and say not only is this the end of an economic cycle, but the end of an era. Culturally, this reminds me more of 2001 than 2008. I remember the way things changed after 9-11, the jingoism, censorship, paranoia etc (in addition to economic decline). I was young at the time, but still remember thinking “Wow the world changed fast and this sh*t is kinda scary.” Most of the changes didn’t happen the day after the towers came down, many were gradual (and the eventual, but not total, thawing took years). It’s going to be interesting to see how things progress over the next year and beyond. Whatever happens, it will be undeniable that the aftereffects of this will be felt for quite some time.
Stay safe out there.
I think you’re probably right, I can’t imagine life being the same after this. Personal hygiene will increase, response to new novel viruses will have to change, we now have new generations that know the market *could* crash if a bad enough virus spreads and containment efforts are weak.
I see what you’re saying all around and agree, and think we WILL see inflation and maybe even high inflation in the USA, but don’t see hyperinflation in USD or at least consider it a de minimis risk (still worth having a bugout bag just for general societal breakdown). Could be wrong. I just haven’t seen betting against the USA ever turn out to be a good long term bet, if for no other reason than other countries will be even more ate up than we are and will cause a flight to quality in USD assets…
…which is still very positive for crypto and gold. As a hodler, I don’t really care if the buyers are coming from America, Asia, or Saturn or Jupiter.
Remember that one Bond movie with Daniel Craig, pretty sure it was Quantum of Solace, where the villain got paid in a briefcase of Euros and said “the dollar isn’t worth what it used to be.” Yeah didn’t age well lol. Not trying to nitpick, fiat is on its way out for sure, just saying.
Deflation before inflation. Think 30s before 70s.
Solid post. This has been my favorite blog ever since you started it years ago.
Bookmarked after reading. I got into sales (SaaS) like you guys advised in a company that is a startup speaking to the trend of remote work. Companies that my friends were interviewing for have pulled offers or just frozen the job hunt as a whole. Right now, I could pay maybe two more months of living expenses (which includes rent) but thankfully stumbled upon a part-time online gig due to a skill I learned.
Things are uneasy at the office even though the company closes big deals, I have been a middle of the line performer and am only still here because my boss likes me but feel like in the past couples months I might have alienated her. Can already tell from tone and body language already.
I think even politically how fucked are too, very likely that Trump loses the election and we get Biden in the White House which is just scary. Cannot get too much into conspiracy here but I genuinely wonder if this was started as the powers that be who wanted to make sure Trump does not get re-elected in 2020, or maybe I am losing it, who the fuck knows.
Scary times ahead, I wonder what will happen to the field of Software Sales. I see remote work becoming the norm here from what I hear as almost all major SaaS companies have gone remote. Getting a new job in this economy even in SaaS will be tough.
Well I picked a terrible time to launch a business. Somehow wised up right before ordering inventory.
Affiliate marketing I return.
Thanks for another insightful post.
It’s been crazy to see people’s lack of understanding of risk, complete inability to think deeply, or consider 2nd, 3rd order consequences.
I’ve seen it with seemingly intelligent friends and colleagues. At this point I want to delete 99% of my personal network and LinkedIn haha
Had the same issue warning coworkers about the posibility of a pandemic since late january, from like 20 or so, only 1 listened and prepared here and there. We still have not gotten to lockdowns yet in mexico, the USD > Peso skyrocketed from 18 to 24, but panic is starting to set in as we near 100 cases in country, most not understanding exponential growth. Gotta thank WSP for the useful advice on this situation
For the next 10 years the debate is going to be — was it worth the economic damage? Many medical experts are saying we will all eventually get exposed to this, and it would take 18 months of social distancing to avoid that. If that is true, then any short to medium term shut down won’t be enough. It will just come back. Meaning we will have the economic damage, and the deaths will happen anyway.
If everyone’s going to eventually get it, then it makes sense to do a full-court press to isolate/protect vulnerable people while letting the economy function. So, yes we are screwed.
This is one of those problems to which there is no easy answer within our complex modern society. I’m glad we’re showing our humanity, in spite of all the jaded ways of our world, by doing our best to prevent suffering and preserve life (unless it backfires and leads to societal breakdown). I could not think of a worse un-thinking person to have in the WH than Trump, but hope the adults in the room prevail.
This is the official stance of the Dutch, UK and German government as well, but they are still not commenting on the long-term ompact on economy. My guess is that from September onwards the real estate market will finally cool down and the next 2 years will be great time to invest in the EU definitely, but WW most likely. Crisis is just another word for opportunity for those who are prepared.
EU is a joke and will likely collapse as a result of this
Laid off from work from Fintech startup! Cutting expenses down to 1k a month. #1 priority will be to fight my company for severance owed and to reach out to network to try and find some work.
Have some savings above 12 months so will be buying gold and btc.
Not Q&A but any clarity on buying timelines if have a pile of excess cash?
No get a new income up first… don’t be crazy this could last a while.
Will do!
Stay safe, guys.
I just wanted to share my appreciation for having your site around. Your content is gold – thank you 🙂
This pandemic is an amazing proof of how irrational people are. Live in Brazil (first death this week) and with everything that is going on around the world people still think this is “just the flu”.
Thanks for the updates.
Guys you have no idea how much of an impact you’ve had on my life. Followed you since 2012/13. Literally 90% of your predictions come true. Everything in my life has been influenced from you.
This is just a short comment to say thank you for being the older brother figure, followed your sales advice, investment advice and now am sitting pretty in this situation. I wish I could contribute back in some way. I’ve already bought all 3 of your products. Keep doing what you’re doing. Saving lives.
Please don’t ever stop this blog.. I don’t know what I would do without it.
Same, early 20s male here, WSPs you have really left a positive impact in my life.
During times of prosper and times of trouble, I look to your blog and to your twitter to ground me.
Stray strong in these turbulent times!
Followed them since ’12 also.
They have always said, thank them by sending the elevator back down.
One day in the future, they will retire but I promise there will be a group of us who will take their place in giving good guidance to a group of 20 somethings who want to live their life to the fullest.
Hey WSP!
I’ll admit I was in the camp of just the flu bros…horribly stupid and insensitive. I do know a doctor who currently works in finance who claims this pandemic will be solved by May. He is either right or horribly wrong. I think he’s especially wrong with how badly this can shake the economy. Point remains I’m listening to a former medical professional, not an airhead reading off a teleprompter. I have backup and am not playing around with this illness…I’m crazy busy so it’s not like I can drop everything and watch the news.
Agreed with some of the commenters here, skill up now. Be alert but don’t be absorbed. There will be a new class of millionaires from this fallout. On the very brief reading I did of this topic it seems to kill off >55 crowd. Nobody knows what the long term effects are of this virus and that has scared me off from certain activities I partake in. I am sitting on assets that will let me buy up homes if I ever choose to step on the gas even more.
Have been upping the vegetables, cleaning routine, and doing what I can do with the certain skills I have at my disposal.
Stay safe out there!
What advise would you give a young man in his early 30’s with …
– US$ 900k in cash
– US$ 200k in the stock market (ETFs globally diversified)
I’m thinking of:
– Setting money aside for 12 months living expenses, which should be US$ 30-40k
– Investing around US$ 100k in gold / crypto as a hedge
– DCA’ing the remaining cash into the stock market over the next 12 months
Assumption is that the markets will sooner or later come back to pre-COVID19 levels. It will be hard to time the bottom, so DCA seems to be a reasonable strategy.
Also, there is a realistic chance that humankind learns how to handle the virus, and we are through the worst in a few months. China & S. Korea proved that the virus can be contained with the right strategies. As long as daily new cases are in the double-digits, the situation seems to be manageable (China today +13 new cases, S. Korea +93 new cases).
Would love to hear your thoughts!
Depends on risk tolerance but since you asked
I’d bump the emergency fund up to $100k. Put it in cash or a short term bond fund and never touch it.
I’d bump the crypto up and the stocks down. “Blue chip” cryptos like BTC and ETH. Gold tends to do well when the anti-inflationary ability of stocks is muted due to bad economic growth, so I’d expect crypto to be similar if not better. Look at past stock market recoveries. These things take longer than 12 months, and this crisis is putting a lot of damage on the system.
I’ll bite (I’m crazy busy and I can’t believe I have to actually follow the news). My background without giving too much away: I have several tens of thousands in the bank and could stop working for a couple years but then again I’d be throwing my life away. Not as much as you are but this is what I probably would do.
Currently stocking up, rereading WSPs material and adjusting to our times. Hint: A business I created is DOA so I will have to make a slight pivot.
Been reading the stock market could drop even more so I’m waiting to DCA. Already DCA into bitcoin.
The absolute kicker I’ve been waiting very patiently on is swooping in on real estate. Kids call this virus the boomer remover. See my comment above on how I was told by a doctor that the pandemic may be gone by May but he surprisingly can’t see the financial world is damaged.
Retool skills and rebuild your network.
Your competition is mostly comprised of people screaming, netflix* and chilling, and hiding in a corner. This crisis will create a new class of millionaires 🙂
*The doctor has a netflix account which I strangely have never signed up for…everybody better start making aggressively cutting down on their expenses.
You would be wise to heed the words of the WSPs and do some research on your own to better understand how China/S. Korea/Taiwan/Honk Kong and others have “contained the virus”
In China they went on a full military lock down and went door to door taking temperatures ripping you out of your home on the spot…no pack a bag, or come down to the quarantine center when you get a chance. They stuffed you in a van and threw you with a bunch of other sick people. They welded apartment doors shut and went zero tolerance full lockdown. That was when they had only 440 cases! The USA is at 10,000 cases and we have only started in the last few days do a mild version of what they did. That was January 23rd I believe. We are going to look a lot like Italy in by April 1st, if not worse…and that’s no joke.
The other countries, they locked boarders immediately to incoming passengers, and have tested tens of thousands along with isolation before it got even the slightest foothold. We are just starting to test and the numbers will dwarf what China reported.
I hope like hell I am wrong, but I would hold cash and a lot of it. Worst case is you “missed” an opportunity to buy cheap, but you are still relatively wealthy for your age and alive. If I am write, you are going to have your first “buying opportunity of a lifetime”. In two years properties will be distressed and good buys will abound. If you want to dip your toe in the market S&P under 2000 is still going to be an excellent buy for someone your age. Hell it is today.
Given your opinion of Stagflationtion or Hyperinflation, regarding Enterprise Sales which would you want to be positioned in:
1) Human Capital Management SAAS sales (pure tech)
2) BPO- Payroll/Benefits/HR Outsourcing (tech with people support)
3) Contractor/Freelance Management SAAS (gig economy tech)
Might be a better Q&A but I have options in a larger stable company, love to hear thoughts on where to lean in.
Thanks
1 or 3
1 if its a new HCM system like Workday or its SMB equivalent
3 what specifically are you selling? who are you competing against?
Good followup questions:
1) Yes full end to end HCM software. Recruiting through Retirement. Including Learning and Talent Activation/Engagement. Midmarket 100-999 space
3) Freelance Management Software. More process based. Organize all your Contractors/Gig workers in a labor cloud, manage everything from contract signing, hours job tracking, invoicing, payment to worker, 1099 processing. All outsource to us via cloud.
Thoughts?
Was set to close on an Investment Property (week to week Vacation Home) in the Outer Banks of North Carolina on April 2nd. Nice place, great rents, was locked in at 3.2%.
Cancelled the contract last week, yesterday they set up a checkpoint at the main bridge. Need to be a resident, Biz owner/employee, Non-Res property holder to enter the county (Dare County – google it). Or apply for a permit . I didn’t bother to check what a permit entails but I’m sure its a bitch.
Local Biz, and Non-Res vacation home owners are going to be crushed this spring/summer. The cancellations are starting.
I dodged a bullet.
Thanks for the information…when the quarantine hits I will be calling people up and buying their property. Yes you dodged a bullet but you’re months, maybe years ahead of buying undervalued housing.
Can only afford 2-5% hedge. Do you mind sharing what you recommend buying?
Crypto portion is covered in Triangle Investing, but consider BTC the standard store of value. Gold you can look into an ETF like SPDR Trust (GLD).
WSPs: Do you recommend buying into crude oil at this time? If you have time, a lot of us would truly appreciate your take on the current oil crisis and its ramifications (heavy supply and demand shocks hitting at same time).
Thank you as always!
Thank you for all the wonderfull advice over the past 2 years i’ve been following you.
You’ve pushed me to start my own business about 2 years ago in construction/ real estate and be hyperproductive (80-hour work weeks efficiently combined with a healthy lifestyle). So far, everything is going well.
At this moment, i was about to invest €600K in a private real estate project.
With the current corona pandemic and its effects on the financial markets, i believe it is best to wait out a major crash in in the real estate market and buy up cheap buildings/ land while keeping my investment money in liquid/ semi-liquid assets (cash, gold, crypto).
Would it be best to;
1) Keep the money in the bank, spread over multiple accounts
2) Spread the money evenly over the bank, gold and crypto (semi-liquid)
3) Spread the money evenly over cash in the bank and crypto?
I ask these questions because i have no experience whatsoever with gold or crypto and am used to immediately reinvest the money i make from my real estate sales. I was only planning on spreading my net worth over multiple assets once i hit the €1M mark. However, with the current coronavirus pandemic, i can obviously not reinvest everything in real estate immediately so i have no idea what the best option is of the above three…
Patiently waiting for your advice.
Thanks!
Well, the game has changed. There is now a widely published, inexpensive cure. I think the end game is near. That means it’s time to bargain hunt.
In investing the bottom is when the second derivative rolls over. Assuming those drugs can be made available, that time is now.
Will never understand why people are worried about the virus.
I think the economic response is catastrophic.
People are shell shocked right now, fighting over toilet paper. They have no Idea what sort of year is approaching us.
1) Peoples wealth effect dissapears 401k down 35%.
2) Business shut down across the board
3) HUGE layoffs
4) Everyone liquidates everything which leads to deflation, on top of this everyone is hoarding CASH, so demand falls further into a deflationary spiral. Whos spending in this enviroment? NO ONE, they’re hoping to hold onto their monthly nut.
The Music stopped, now they’re floating draconian martial laws, shut downs, helicopter money…etc.
Good luck people, stay safe.
If things get bad enough that people would use gold as money well then they wouldn’t use gold as trading but they will trade things like food, supplies etc
Long time reader at a megafund PE shop – 27 and ~$800k net worth. Thoughts on timing to buy a cheap apt in nyc?
I’ve got a pre-approval bank letter for 3.25% / 80% LTV for a ~$500k 1 BR in manhattan. Monthly condo fees (~$1,000) + taxes + mortgage would be less than my current 1 BR rent. I have another smaller line of income (section 8 housing) and while I have been top bucket, who knows what happens to the PE firms overall. I recognize that I could make higher alpha returns by renting and investing my downpayment outside nyc at higher IRRs, but I also think I’m bidding a bank low on a co op apartment they own and want off their books and this is a way for me to deploy capital into a well-priced hard asset when the economy may cycle. I also think even if I lose my job, it lowers my monthly expenses vs renting. A bit of convenience factor vs constant alpha generation, and buying a hard asset at would could be an opportunistic time
Not a Q&A…